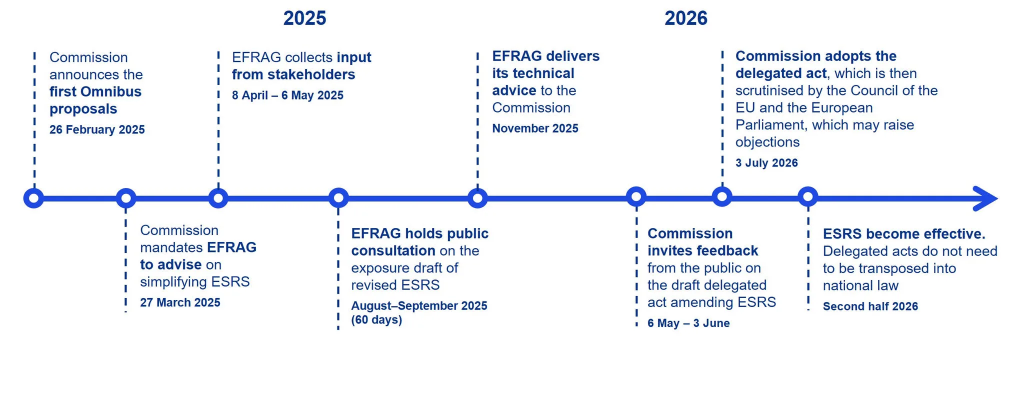
On 3 July 2026, the European Commission formally adopted the revised ESRS as part of the Omnibus I legislative package.
The key simplifications were already included in the May draft: over 60% fewer mandatory datapoints, more than 70% fewer datapoints overall, and approximately 30% lower costs per company.
The July step was largely a formal fine-tuning—featuring a few substantive clarifications regarding human rights and data-request limits across the value chain.
Timeline of Entry into Force and Practical Application
-
Publication: The regulation was published in the Official Journal of the European Union on 21 September 2026.
-
Revised mandatory ESRS standards (Delegated Regulation (EU) 2026/1563): Entered into force on 10 November 2026.
-
Start of mandatory application: The revised ESRS standards must be applied for financial years beginning on or after 1 January 2027.
-
Transitional rule for the 2026 financial year: For the 2026 financial year, companies may choose whether to apply the original ESRS, its simplified version, or the new, revised ESRS in its entirety.
The regulation is available here.
What was decided on 3 July 2026? The Commission adopted the revised ESRS for companies subject to the CSRD, along with the voluntary VS Standard for entities reporting on a voluntary basis. Both form part of the first Omnibus package, through which the EU intends to substantially streamline sustainability reporting.
-
More than 60% fewer mandatory datapoints compared to the previous ESRS package
-
Over 70% fewer datapoints in total (combining mandatory and voluntary)
-
Around 30% lower costs per reporting company
-
A significantly leaner structure, fewer overlaps, and greater flexibility
Under the S1–S4 social standards, human rights incidents must now be substantiated and confirmed to trigger reporting obligations. “Confirmed” status requires an official determination—such as by a court, an OECD National Contact Point grievance mechanism, or a public authority.
For in-scope companies, the revised ESRS brings tangible relief: fewer mandatory datapoints, an extended phase-in period for E1-11, and greater freedom in structuring the report. Furthermore, the stricter threshold for human rights incidents reduces research and data collection burdens across social standards.
However, the double materiality assessment remains the cornerstone of reporting. It determines which of the reduced datapoints are genuinely material to the company.
Following publication in the Official Journal, the text is finalized—processes can now be tailored directly to the revised ESRS. Companies are advised to decide early which version to apply for the 2026 financial year, prioritizing materiality, databases, and reporting workflows.
The recommended next step: With legal clarity now established, align materiality assessments and databases with the final text—and determine which ESRS version will be applied for the 2026 financial year.
-
Shortening and clarifying the text of the standards
-
Introducing new, additional flexibility mechanisms
-
Reducing the number of mandatory datapoints in the standards by 61%
-
Improving the interoperability of the revised ESRS with international standards and other EU legislation
-
Simplifying the materiality assessment
-
The final delegated regulation
-
Annex I to the delegated regulation, containing the ESRS standards themselves
-
Annex II to the delegated regulation, containing the list of acronyms and the glossary of terms
-
The Commission Staff Working Document accompanying the delegated regulation
What Are the Significant Changes?
Fair Presentation
Practical Considerations
-
Stating that an undertaking is not required to assess every conceivable IRO across its entire operations and upstream/downstream value chain to identify material topics.
-
Allowing the undertaking to use reasonable and supportable information available without undue cost or effort.
-
Enabling the undertaking to draw conclusions regarding whether an IRO is material based on its strategy, business model, operating sectors, geographic location, and specific characteristics of its value chain—establishing the option to conduct the assessment using either a top-down or a bottom-up approach.
-
Allowing the undertaking not to evaluate every time horizon or individual severity criterion for every IRO if it determines that no further assessment is needed to reach a materiality conclusion.
Materiality of Information
-
Primary users of general-purpose financial reports: current and potential investors, lenders, and other creditors, including asset managers, credit institutions, and insurance undertakings.
-
Other users of general-purpose sustainability statements: business partners, trade unions, social partners, civil society, and non-governmental organizations (NGOs).
Disaggregation
Reporting Reliefs and Exemptions
Acquisitions and Disposals
-
An undertaking may elect to defer including a newly acquired subsidiary in its sustainability statement until the following reporting period.
-
An undertaking that disposes of a subsidiary during the reporting period may choose to “adjust the scope of the materiality assessment and reporting boundaries” from the beginning of the current reporting period.
-
Where an undertaking relies on this relief, it must disclose, using available information, any significant events affecting the subsidiary during the reporting period that impacted the group’s IROs.
Value Chain Information
Undue Cost or Effort
-
Identify material IROs
-
Determine the scope of the value chain
-
Determine what value chain information should be included in the sustainability statement
-
Prepare metric-related disclosures
-
Report current and anticipated financial effects
Calculation of Metrics
Investment Management Entities
Reporting Boundary
-
Immaterial subsidiaries: An undertaking may exclude an immaterial subsidiary from its sustainability statement, unless that subsidiary exposes the group to material impacts.
-
Leased assets: Lessees present impacts related to the use of leased assets as part of their own operations, while lessors report impacts related to the use of leased assets within their downstream value chain. Risks and opportunities associated with leased assets, as well as impacts related to asset ownership, may be shared between lessor and lessee.
-
Long-term employee benefit funds: IROs arising from assets held in an undertaking’s long-term employee benefit plans must be reported as part of the upstream value chain.
-
Joint operations: Undertakings may exclude information from joint operations over which they do not exercise operational control from the scope of environmental metrics under ESRS E2, ESRS E3, ESRS E4, and ESRS E5.
Structure of the Sustainability Statement
-
An executive summary containing key messages regarding the undertaking’s material impacts, risks, or opportunities;
-
A separate annex dedicated to EU Taxonomy disclosures;
-
Annexes for more detailed information, tables of contents, supplementary data, and mapping/cross-reference tables.
Anticipated Financial Effects
-
The undertaking is not required to disclose quantitative information on anticipated financial effects if those effects are not separately identifiable, or if “the measurement uncertainty associated with estimating the effects is so high that the resulting quantitative information would not be useful.”
-
The undertaking is not required to provide quantitative information if it lacks the “skills, capabilities, or resources” necessary to do so.
-
Undertakings are permitted to present quantitative information either as single amounts or as ranges.
Omission of Information
-
In exceptional cases, if disclosure “would be seriously prejudicial to the commercial position of the undertaking”;
-
If it relates to “intellectual capital, intellectual property, know-how, technological information, or results of innovation,” provided it constitutes a trade secret;
-
If classified (state secret / protected) information is involved;
-
If disclosure is otherwise restricted “under other EU legislation or national law to protect against unauthorized access or disclosure, or to safeguard the privacy or security of natural persons or the security of legal entities.”
General Disclosure Requirements (GDRs)
Transitional Provisions
-
“Wave one” entities: Undertakings required under the CSRD to report on sustainability matters for financial years beginning between 1 January 2024 and 31 January 2026;
-
“Other” entities: Undertakings required under the CSRD to report on sustainability matters for financial years beginning on or after 1 January 2027.
Updates to Topical Standards
| ESRS (2026) | Summary of Changes |
| ESRS E1 (2026) Climate Change (AR 19) | ESRS (2023) required undertakings to report greenhouse gas (GHG) emissions using organizational boundaries combining financial and operational control. ESRS (2026) establishes that undertakings may choose between financial control, operational control, or the equity share approach. ESRS 1 (2026) also notes that the ESRS 1 guidance on leases, long-term employee benefit schemes, and joint operations must be followed when setting GHG reporting boundaries. |
| ESRS E2 (2026) Pollution (Paragraph 15 and AR 2) | The requirement to disclose each individual pollutant released to air, water, and soil listed in the European Pollutant Release and Transfer Register (E-PRTR) has been deleted. To identify reportable pollutants, ESRS E2 (2026) requires a “managerial assessment” considering operations and active sectors. |
| ESRS E2 (2026) (Paragraph 16) | ESRS E2 (2026) scales back the ESRS E2 (2023) requirements concerning microplastics produced or used. While retaining disclosure obligations, it clarifies that undertakings report on primary microplastics manufactured or used in products, separately detailing primary microplastics released directly to the environment. |
| ESRS E2 (2026) (Paragraphs 18–20) | Disclosures regarding Substances of Concern (SOC) and Substances of Very High Concern (SVHC) have been updated: Manufacturers and importers must disclose total weight of SOC procured, manufactured, placed on the market, and released directly to the environment, and separately the total weight of SVHC. Users of substances must only disclose the total weight of SVHC used in production and service delivery, plus SVHC released directly to the environment. Manufacturers, importers, and users of articles containing SVHC must disclose the names of SVHC present in purchased or marketed components or articles exceeding 0.1% by weight. |
| ESRS E3 (2026) Water | The term “marine resources” and related topics have been removed from ESRS E3. ESRS E5 (2026) now references marine resources as a category of resource inflows. |
| ESRS E4 (2026) Biodiversity and Ecosystems (Paragraph 21) | Clarified the obligation to report metrics under ESRS 2 (2026) GDR-M, including metrics on material impacts on biodiversity and ecosystems. |
| ESRS E5 (2026) Resource Use and Circular Economy (Annex II) | ESRS E5-4 (Resource inflows) introduces the concepts of “key materials” (essential for production processes and generating products/services) and “key products” (central to value creation or strategic objectives). |
| ESRS S1 (2026) Own Workforce (Paragraph 20(a) and 24(b)) | ESRS S1-5 and ESRS S1-7 provide an updated threshold for determining whether employment in a country is “significant”: countries where headcount is 50 or more and that rank among the top 10 countries by employee headcount. |
| ESRS S1 (2026) (AR 20(b)) | For non-EU countries, the hierarchy for establishing an adequate wage has been amended to: Statutory collective bargaining wages that “provide a decent standard of living, as confirmed by calculation in line with ILO living wage estimation principles as a minimum floor”; Any existing living wage estimate considering ILO principles. |
| ESRS S1 (2026) (AR 36 and AR 37) | In disclosures on discrimination and other human rights incidents, the concept of “severe” incidents was deleted; only “substantiated and confirmed” incidents must be reported. Guidance is provided on when an incident is deemed substantiated or confirmed. |
| ESRS G1 (2026) Business Conduct | Reorganized into a streamlined structure: divided into dedicated sections for policies, actions, targets, and metrics. Several datapoints within these sections were deleted or merged. |
Structural Changes to the Standards
-
Mandatory requirements have been moved into the main body of each standard. Voluntary disclosures have been deleted or rephrased as Application Requirements (AR). “May”-type disclosures retained in the standards or ARs offer presentation options or flexibility, but do not constitute standalone datapoints.
-
Application Requirements have been condensed and positioned directly in the main body alongside their respective disclosure requirements, including specific paragraph cross-references.
-
Topical standards in ESRS (2023) contained supplementary disclosure and application requirements tied to ESRS 2 GOV-1, GOV-3, IRO-1, SBM-2, and SBM-3, which complicated application. These were either consolidated into ESRS 2 (2026) or deleted.
When Can Undertakings Apply ESRS (2026)?
-
Apply ESRS (2023), as amended by the “Quick Fix” delegated act extending certain transitional provisions;
-
Apply ESRS (2026) in its entirety;
-
Apply ESRS (2023) as amended by the “Quick Fix” delegated act, combined with selected reliefs and options adopted from ESRS (2026).
What Comes Next?
Transitional Provisions in ESRS (2026)
| ESRS Disclosure Requirement or Datapoint | Transitional provision for “wave one” entities with net turnover > €450M and > 1,000 employees | Transitional provision for “wave one” entities not exceeding €450M turnover or 1,000 employees | Transitional provision for “other” entities |
| Value chain information | In the first 3 years of reporting, if unable to obtain all required value chain data, disclose efforts made, reasons for missing information, and future plans to obtain it. | In the first 3 years of reporting, if unable to obtain all required value chain data, disclose efforts made, reasons for missing information, and future plans to obtain it. | In the first 3 years of reporting, if unable to obtain all required value chain data, disclose efforts made, reasons for missing information, and future plans to obtain it. |
| Comparative information | May be omitted in year 1, except for metrics and figures required identically by ESRS (2026) and ESRS (2023). | May be omitted in year 1. | May be omitted in year 1. |
| All disclosure requirements for: ESRS E4, ESRS S2, ESRS S3, ESRS S4 | May be omitted for financial years prior to 2027. However, the disclosures in ESRS 2 (2026) paragraphs 7–10 must still be provided. | Not applicable | May be omitted for the first 2 financial years of reporting. However, the disclosures in ESRS 2 (2026) paragraphs 7–10 must still be provided. |
| All disclosure requirements of all topical standards | Not applicable | May be omitted for financial years prior to 2027. However, the disclosures in ESRS 2 (2026) paragraphs 7–10 must still be provided. | Not applicable |
| All information on anticipated financial effects required by ESRS 2 and ESRS E1 (except ESRS E1 paragraphs 39(a)–(b) and 40(a)–(b)) | May be omitted for financial years prior to 2028. | May be omitted for financial years prior to 2028. | May be omitted for the first 2 financial years of reporting. |
| Quantitative information on anticipated financial effects required by ESRS 2 and ESRS E1 (except ESRS E1 paragraphs 39(a)–(b) and 40(a)–(b)) | May be omitted for financial years prior to 2030. | May be omitted for financial years prior to 2030. | May be omitted for the first 4 financial years of reporting. |
| Quantitative information on Substances of Concern required by ESRS E2-5 | May be omitted for financial years prior to 2030. | May be omitted for financial years prior to 2030. | May be omitted for the first 3 financial years of reporting. |
| Information on Substances of Very High Concern when the undertaking is a user of articles containing such substances | May be omitted for financial years prior to 2028. | May be omitted for financial years prior to 2028. | May be omitted for the first financial year of reporting. |
|
Selected disclosures in ESRS S1:
• Characteristics of non-employee workers (S1-6)
• Collective bargaining and social dialogue outside EEA (S1-7)
• Social protection (S1-10)
• Persons with disabilities (S1-11)
• Training and skills development metrics (S1-12)
• Health and safety metrics for non-employees (S1-13)
• Work-related ill health and lost days due to occupational injuries and illnesses (S1-13)
• Work-life balance metrics (S1-14)
|
May be omitted for financial years prior to 2027. | May be omitted for financial years prior to 2027. | May be omitted for the first financial year of reporting. |
ESMA Publication
https://finance.ec.europa.eu/news/commission-adopts-revised-sustainability-reporting-standards-2026-07-03_enhttps://viewpoint.pwc.com/us/en/pwc/in-depth/2026/id_int202603.html#glance1
https://finance.ec.europa.eu/news/commission-adopts-revised-sustainability-reporting-standards-2026-07-03_en